Non-QM loans in Phoenix help buyers who can afford a mortgage but fail conventional underwriting overlays. The return is thin because the business writes off everything it legally can. There is an ITIN instead of a Social Security number. Income is deposits, not a W-2. Giancarlo Anduray at AFM Lending originates Non-QM and ITIN files when those facts are documented. The point of this post is what you actually need to bring, and what those programs will not do.
Start with the honest constraint. If you do not have a Social Security number, say that first. If you have an ITIN and filed returns, that is a different file from a foreign-national purchase with overseas income. Mixing those lanes wastes a week. If you have a Social Security number and a business that does not show enough on the 1040, the conversation is bank statements, a P and L, or a DSCR rental, not an ITIN product.
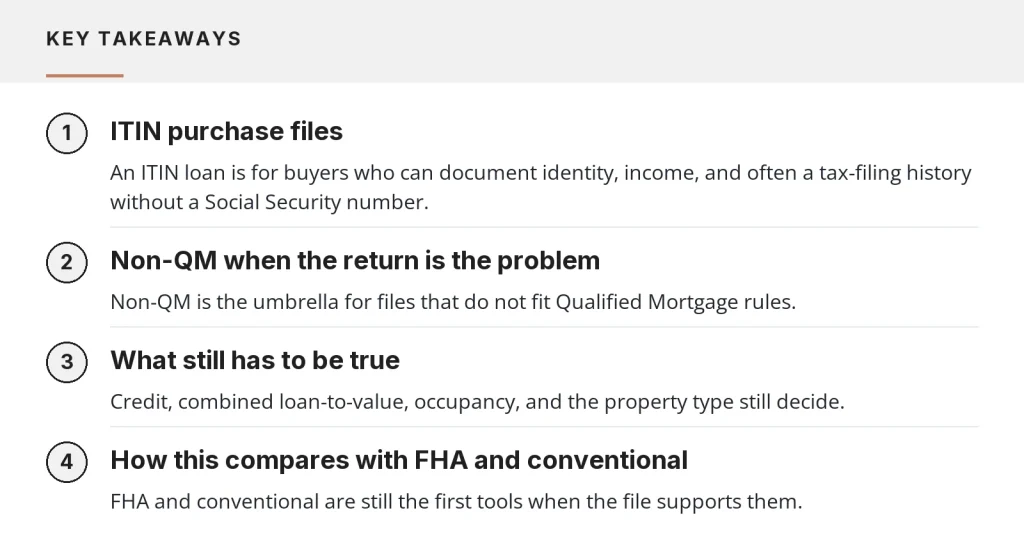
ITIN purchase files
An ITIN loan is for buyers who can document identity, income, and often a tax-filing history without a Social Security number. Credit still matters. Down payment still matters. The house still has to appraise and the occupancy has to match the program. Nothing here is a public promise that every ITIN applicant in Phoenix will close.
What to bring: the ITIN assignment letter, photo ID, two years of returns if they exist, bank statements, and a target payment. If returns were not filed, that is the first problem to name. Some files can use alternative income documentation. Some need the filings done before an underwriter will look. Giancarlo will tell you which one you are in before you write an offer in Glendale or the West Valley.
Using Non-QM Loans in Phoenix When Tax Returns Are a Problem
Non-QM is the umbrella for files that do not fit Qualified Mortgage rules. In this shop that usually means bank-statement income, a single-page P and L, or DSCR on an investment property where the rent has to cover the payment. It is not a way around a recent bankruptcy, a house that will not appraise, or reserves you do not have.
Bank-statement files typically want 12 months of deposits, sometimes 24. Underwriters will haircut ineligible deposits. If your Phoenix business mixes personal and business accounts, clean that up before you apply or expect a slower review. DSCR files want a lease or a rent schedule and a property that actually cash-flows after taxes, insurance, and HOA. A short-term rental story needs numbers, not a screenshot of calendar occupancy.
What still has to be true
Credit, combined loan-to-value, occupancy, and the property type still decide. Condos, non-warrantable projects, and unique West Valley property types can stop a file that looked fine on income alone. Insurance in Maricopa County is part of the payment. A quoted rate without a full PITI is not a quote.
Spanish-speaking families can run this whole process in Spanish. Hablamos Espanol. The document list does not get simpler because the conversation is in Spanish. It just gets explained without a translator in the middle.
How this compares with FHA and conventional
FHA and conventional are still the first tools when the file supports them. Lower mortgage insurance or a cleaner guideline set beats a Non-QM price for many W-2 buyers. The mistake is staying in that lane out of habit when the return cannot support it. The other mistake is jumping to Non-QM because it sounds flexible, then discovering the rate and the reserve requirement are worse than filing the return and using FHA.
That comparison is the first-call job. Bring the constraint, the city, and the payment you can actually carry. Call (623) 552-4191 or visit afm.loans to explore Non-QM loans in Phoenix and see which lane fits your situation. Giancarlo Anduray, NMLS #1537433. AFM Lending. Equal Housing Lender. All loans subject to credit approval. Programs and guidelines can change. This is not a commitment to lend.