For any first-time home buyer in Phoenix AZ, a common question is whether you can buy a house if you have not filed your taxes. The honest answer is that it depends on the loan program and on how you earn your income. What matters most is finding out where you stand before you start touring homes, so the file you bring to a lender is complete and the timeline holds.
Why tax returns matter to a mortgage file
Many loan programs rely on tax returns to document income. Underwriters use them to confirm what you earn, how stable it is, and whether the figures match your pay stubs, bank statements, and other records. When a return is missing, there is a gap in that picture, and the file usually cannot move forward until the gap is closed.
That does not mean the door is shut. It means the first conversation should be about which years are missing, why, and what can be done to bring the paperwork current.
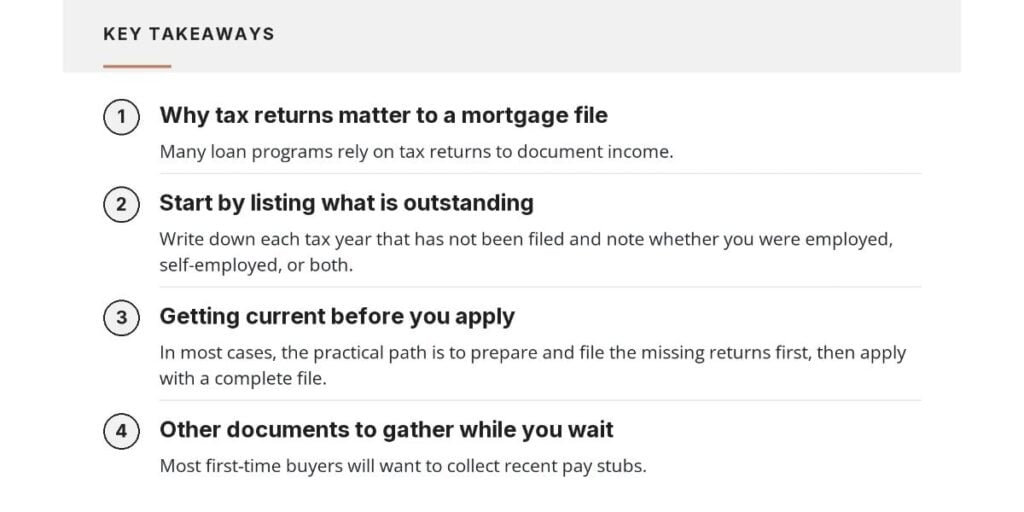
Start by listing what is outstanding
Write down each tax year that has not been filed and note whether you were employed, self-employed, or both. Some buyers have only the most recent year outstanding. Others have a few years behind. Knowing the exact list makes every later step quicker, because a loan advisor and a tax professional can look at the same facts.
Getting current before you apply
In most cases, the practical path is to prepare and file the missing returns first, then apply with a complete file. If any balance is owed, a payment arrangement may come into play, and that can affect how the file is reviewed. A tax professional is the right person to advise on that part. A loan advisor can then explain how the result changes your loan options.
This is where working with a team that looks at both sides helps. Giancarlo Anduray co-owns Mi Casa Tax Advisors, so the mortgage conversation and the tax conversation can use the same numbers instead of happening in two separate offices.
Documents for a First-Time Home Buyer in Phoenix AZ
Filing takes time, so use it. Most first-time buyers will want to collect recent pay stubs, two months of bank statements for every account that will cover the down payment and closing costs, a government photo ID, and a list of current monthly debts. Self-employed buyers should also keep business bank statements and any profit and loss records together in one folder.
Large or unusual deposits often need a short written explanation, so it helps to know where that money came from. Gifts from family should be documented with a gift letter and a paper trail.
Know your monthly payment, not only the price
Once the paperwork is on track, look at the full monthly payment. Principal and loan costs are one piece. Property taxes, homeowners insurance, mortgage insurance on some loans, and any HOA dues all add to it. In the Phoenix and Glendale areas those items can differ by neighborhood and by property type, so ask for estimates early.
A useful way to plan is to decide on a monthly payment you are comfortable with, then work backward to a price range. That keeps the search realistic and avoids surprises later in underwriting.
Compare loan types with your real numbers
FHA, conventional, and VA loans each have their own rules for down payment, credit, and mortgage insurance. Arizona also has down payment assistance programs that some buyers qualify for, and eligibility depends on the program. The right comparison happens once your income documents are complete, because the numbers drive which option fits.
Keep your finances steady
While you are getting the file in order, try to avoid opening new credit accounts, financing a vehicle, or making large purchases on credit. Changes like these can shift your debt picture right when a lender is reviewing it. If something does change, mention it early so it can be handled without delay.
Talk it through before you shop
If you are a first-time home buyer in Phoenix AZ with unfiled taxes, a short conversation can map out the order of steps.AFM Lending offers service in English and Spanish, and Giancarlo goes by Gian with clients. Call (623) 552-4191 or visit afm.loans to start with your own situation.
Giancarlo Anduray, NMLS 1537433. AFM Lending, powered by PMR. All loans subject to credit approval and underwriting. Equal Housing Lender.