How business write-offs affect a self-employed mortgage in Phoenix
Securing a self-employed mortgage in Phoenix AZ often feels harder than it should for business owners, freelancers, and independent contractors.The reason is usually not a lack of income. It is the way income is documented. Deductions that lower a tax bill can also lower the income a lender is able to count on a conventional loan.
Why take-home and qualifying income can differ
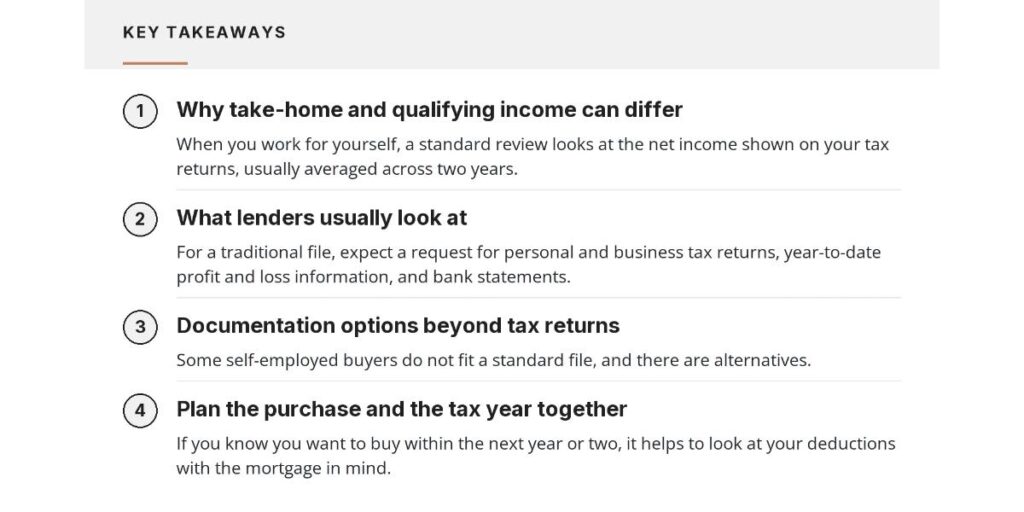
When you work for yourself, a standard review looks at the net income shown on your tax returns, usually averaged across two years. Business expenses, vehicle costs, home office deductions, and depreciation all reduce that net figure. Those write-offs are legitimate and often smart for taxes. They can still leave a buyer with qualifying income that looks smaller than the money actually coming in
What lenders usually look at
For a traditional file, expect a request for personal and business tax returns, year-to-date profit and loss information, and bank statements. Reviewers look for stable or growing income over time. If income dipped in one year, they may ask for an explanation. Having this paperwork organized before you apply makes the process calmer for everyone.
Documentation Options for a Self-Employed Mortgage in Phoenix AZ
Some self-employed buyers do not fit a standard file, and there are alternatives. Bank statement programs review deposits over a set period instead of relying only on net tax return income. Other non-QM options exist for specific situations, such as investors who qualify on property income. Each has its own down payment, credit, and documentation requirements, and each comes with tradeoffs compared with a conventional loan. A loan advisor can lay those out using your actual records.
Plan the purchase and the tax year together
If you know you want to buy within the next year or two, it helps to look at your deductions with the mortgage in mind. Decisions that make sense for one tax year may change how your income reads to an underwriter. That is a conversation worth having early, before returns are filed, not after.
Giancarlo Anduray co-owns Mi Casa Tax Advisors, so the loan side and the tax side can be reviewed together. The tax advisors speak to your tax position, and the loan advisor speaks to how a lender will read the result. Neither replaces the other, and having both in the same conversation saves time.
Steps to take before you apply
A few habits make a self-employed file much easier to process. Keep business and personal accounts separate. Deposit business income into a consistent account. Keep your profit and loss statement current. Save invoices or contracts that show ongoing work. And keep records of any large deposits so you can explain them.
Think about the whole monthly payment
Whichever documentation route fits, look at the complete monthly cost of the home. Property taxes, homeowners insurance, mortgage insurance on certain loans, and HOA dues all belong in the budget. Phoenix and Glendale neighborhoods vary, so get estimates for the specific areas you are considering.
Start with a clear picture of your file
If you need a self-employed mortgage in Phoenix AZ, a short review of your documents can show which loan paths are realistic and what to prepare. AFM Lending works with self-employed buyers and serves clients in English and Spanish. Call (623) 552-4191 or visit afm.loans to talk through your situation with Gian.
Giancarlo Anduray, NMLS 1537433. AFM Lending, powered by PMR. All loans subject to credit approval and underwriting. Equal Housing Lender.